Home insurance in Boca Raton, explained properly
What actually drives your premium here, how hurricane deductibles work in dollars, and why roof age decides more than almost anything else.
We're an independent agency, which means we don't work for one carrier. We compare offers across 30+ companies for homeowners in Palm Beach, Broward, and Miami-Dade Counties. This page isn't a sales pitch. It's the reference we wish existed when a Boca homeowner opens a renewal with a large increase, or a buyer finds out they need a binder before Friday's closing.
Why two houses on one street price thousands apart
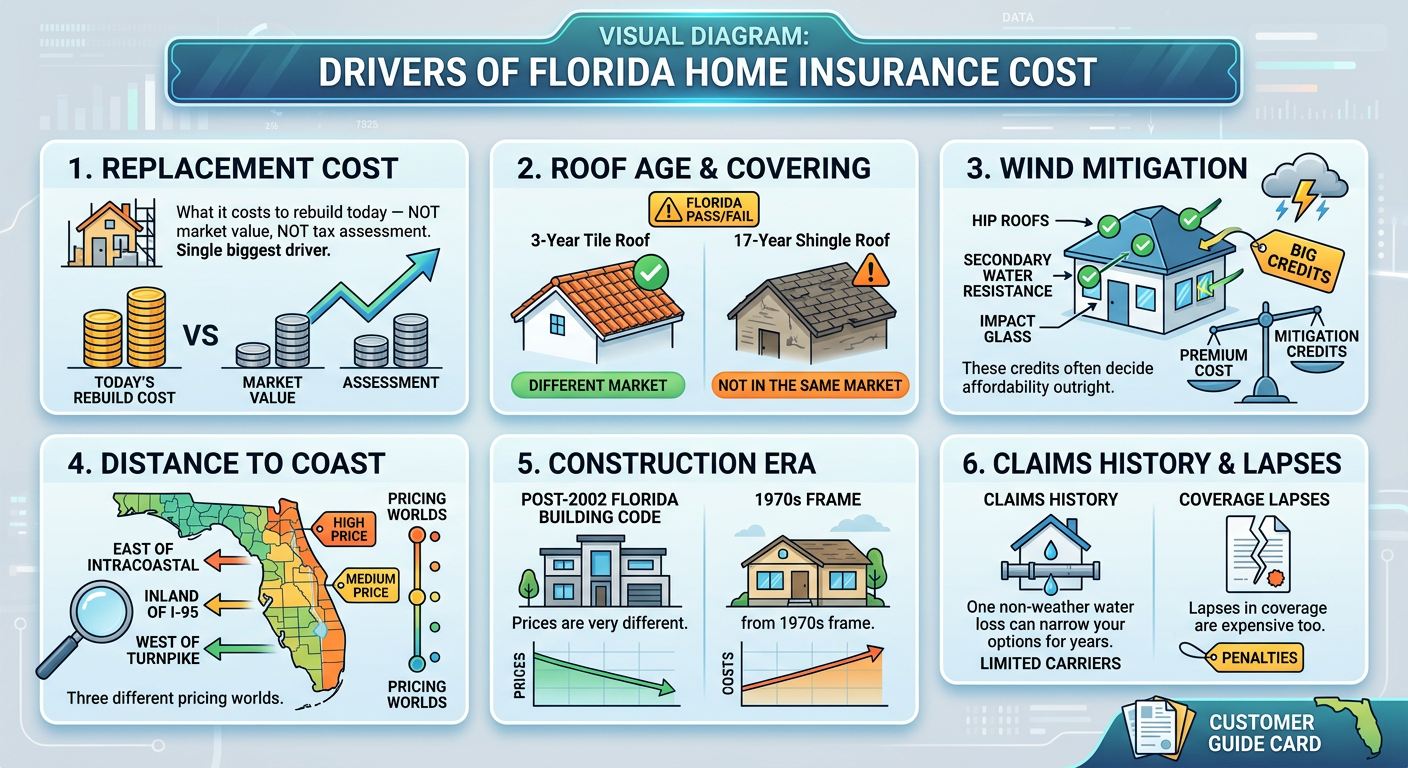
There is no single "Boca Raton rate." Here's what carriers actually weigh, in rough order of impact.
Replacement cost
What it costs to rebuild today: not market value, not the tax assessment. The single biggest driver.
Roof age and covering
Close to pass/fail in Florida. A 3-year tile roof and a 17-year shingle roof aren't in the same market.
Wind mitigation
Hip roofs, secondary water resistance, impact glass. These credits can make the difference in affordability.
Distance to coast
East of the Intracoastal, inland of I-95, and west of the Turnpike are three different pricing worlds.
Construction era
Post-2002 Florida Building Code construction prices very differently from 1970s frame.
Claims history
One non-weather water loss can narrow your options for years. Lapses in coverage are expensive too.
How Florida hurricane deductibles actually work
Your policy has two deductibles: a standard one for everyday claims, and a separate hurricane deductible set as a percentage of your dwelling limit. Move the slider to see it in dollars.
A kitchen fire runs through the standard deductible. A named hurricane that takes the roof runs through the hurricane deductible instead: same house, same policy, very different first check. The $2,500 standard deductible is an example only. Yours is shown on your declarations page.
Lowering the percentage lowers your out-of-pocket exposure and raises your premium; raising it does the reverse. In Florida, the hurricane deductible generally applies once per calendar year. If a second hurricane causes a claim in the same year, you typically pay the greater of your standard deductible or whatever remains of your hurricane deductible, not a fresh hurricane deductible.
Your homeowners policy probably doesn't cover flood
A standard homeowners policy does not cover flood. Not in Boca Raton, not anywhere, even when the water arrives with a hurricane. Rising water, storm surge, and water flowing across the ground into your home are flood losses. Some carriers let you add flood coverage to your homeowners policy by endorsement. If yours doesn't, you'll need a separate flood policy through the NFIP or a private flood insurer.
With a separate flood policy, one hurricane can produce two claims, under two policies, with two deductibles and two adjusters. Even with a flood endorsement, flood losses often carry their own deductible and limits, so it's worth comparing an endorsement against a standalone policy. Read our Boca Raton flood insurance guide →
Water damage, sorted out
| What happened | Who pays | Watch for |
|---|---|---|
| Burst supply line, failed water heater | Homeowners | Often has a sublimit or separate water deductible |
| Long-term seepage or gradual leaks | Excluded | Carriers expect maintenance |
| Rain through a storm-created opening | Homeowners | Not covered through an existing gap or worn roof |
| Sewer or drain backup | Endorsement | Never automatic, so ask for it by name |
| Rising water, surge, ground flooding | Flood coverage | Separate flood policy, or a flood endorsement if your carrier offers one |
Roof age and Florida law
Many carriers restrict or decline shingle roofs approaching 15 years. Tile roofs are often accepted up to around 25 years, and metal also usually has longer runway than shingle. Florida law §627.7011 limits an insurer's ability to refuse or non-renew solely because of roof age when the roof is under 15 years old, or when an authorized inspection shows at least five years of useful life remaining.
A note on the 2026 session. Several sites claim a new Florida law took effect July 1, 2026 expanding roof-age protection to all residential policies. Those bills, HB 815 and SB 808, died in committee on March 13, 2026 and never became law. The 2022–2023 protections above are still the operative rule.
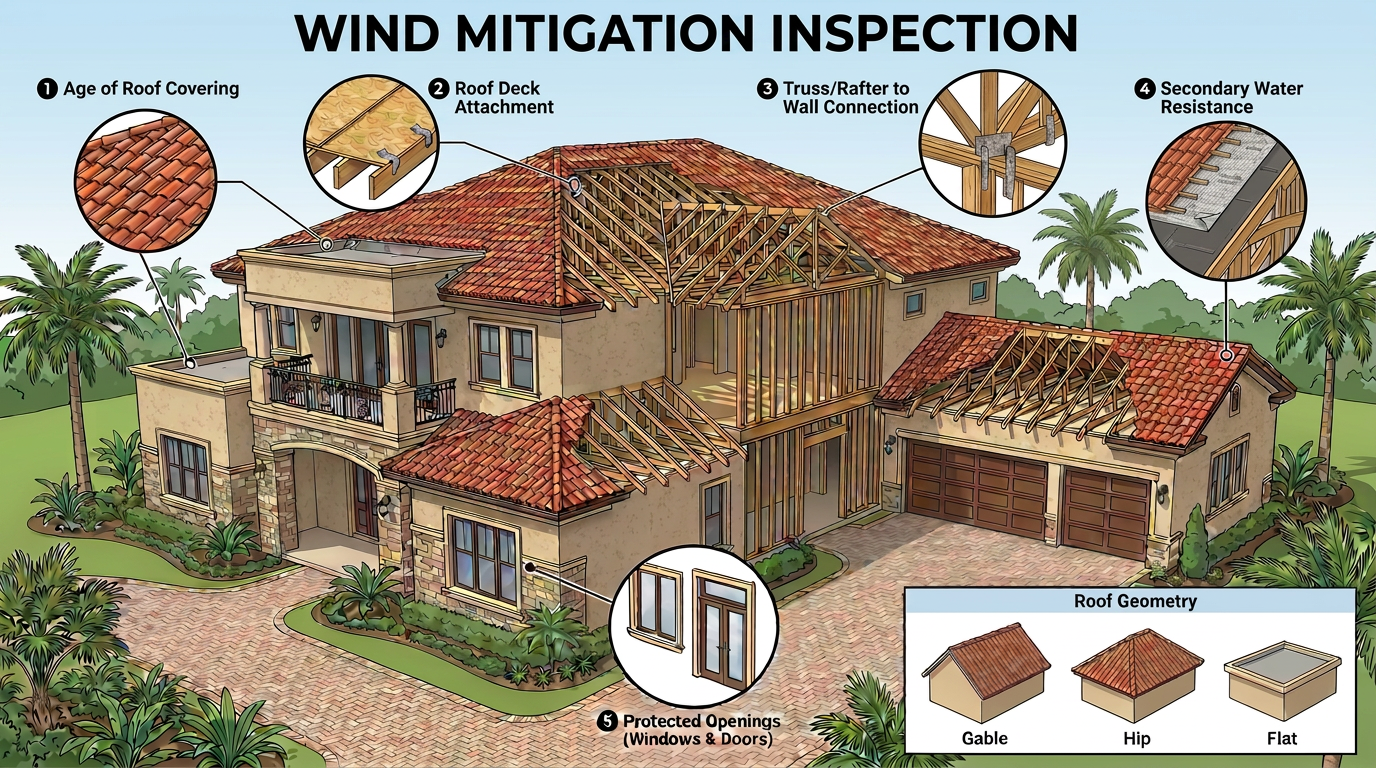
Settlement matters too. Some policies pay roof losses at replacement cost; others switch to actual cash value once the roof hits a certain age. On a $40,000 roof that difference can run to tens of thousands, and it's usually buried in an endorsement rather than printed on the declarations page.
If your roof is 12 or 13 years old, that's the moment to call us. Not at 16.
Boca Raton, area by area
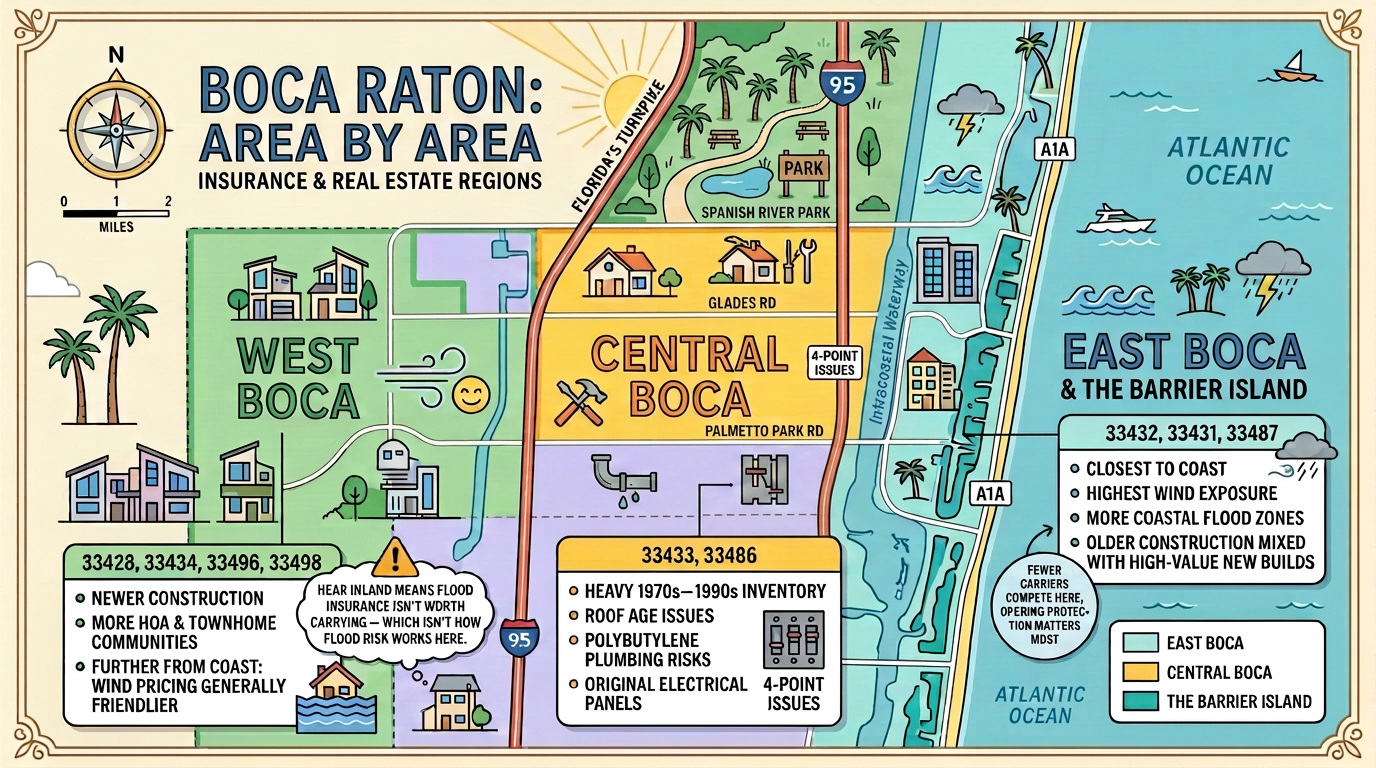
East Boca & the barrier island
Closest to the coast, highest wind exposure, more coastal flood zones, older construction mixed with high-value new builds. Fewer carriers compete here, and opening protection matters most.
Central Boca
Heavy 1970s–1990s inventory. Roof age, polybutylene plumbing, and original electrical panels are the recurring 4-point issues.
West Boca
Newer construction, more HOA and townhome communities, further from the coast so wind pricing is generally friendlier. Also where we most often hear that inland means flood insurance isn't worth carrying, which isn't how flood risk works here.
Beyond Boca Raton
We write homes across Palm Beach, Broward, and Miami-Dade. Each nearby city has its own coverage issues:
Have your current declarations page?
Skip the forms. Email your current home or flood declarations page to [email protected] and we'll shop it across 30+ carriers. We typically have options for you by the next business day.
Email Your Dec PageBoca Raton home insurance FAQs
Does homeowners insurance cover hurricane flooding?
Not under a standard homeowners policy. Wind damage from a hurricane is covered, but flooding, including storm surge and rising water, is excluded. Some carriers offer flood coverage as an endorsement you can add to your homeowners policy. If yours doesn't, you'll need a separate flood policy. Either way, wind and flood damage from the same storm may be settled with different deductibles.
What is a Florida hurricane deductible?
A separate deductible, commonly 2%, 5%, or 10% of your dwelling coverage limit, that applies only to hurricane losses instead of your standard deductible. On a $600,000 dwelling limit, a 2% hurricane deductible is $12,000. It generally applies once per calendar year.
How old can my roof be and still get insured in Florida?
It depends on the covering and the carrier. Shingle roofs generally face restrictions as they approach 15 years, while tile roofs are often accepted up to around 25 years and metal also typically has longer runway. Florida law limits refusal based solely on roof age when the roof is under 15 years old, or when an authorized inspection shows at least five years of useful life remaining.
What is a 4-point inspection?
An inspection of a home's roof, electrical, plumbing, and HVAC systems that many Florida carriers require on older homes before they will write coverage. The age that triggers it varies by carrier, often starting around 20 years.
Is a wind mitigation inspection worth it?
For many Boca Raton homeowners, yes. The resulting credits often more than pay for the inspection, though savings depend on your home's features and your carrier. The report is filed on Florida's uniform form OIR-B1-1802 and is generally valid for five years.
Is Citizens my only option?
Frequently not. Citizens is Florida's insurer of last resort, and the private market has expanded since 2023. If you were placed in Citizens more than a year ago, it's worth re-shopping.
Can you help if I need a binder quickly?
Yes. Send us the address, the contract date, and any inspection reports you have, and we'll tell you what's realistic on your timeline.
Let's compare your options
30+ carriers, one conversation. Independent agency in Boca Raton since 1993.
Get a home insurance quote Call (561) 479-1898*Quote turnaround applies when you email a current declarations page during business hours (Monday–Friday, 9am–5pm) and varies with carrier response times.
This guide is general information about Florida property insurance. It is not a quote, an offer of coverage, or legal advice. Coverage, eligibility, and pricing vary by carrier, policy form, and individual property, and Florida insurance law changes frequently. Only your policy documents govern your coverage. Cronin Insurance Agency, Boca Raton, FL.