What the rental counter is actually selling
The products offered at the counter are not one thing, and only some of them are insurance.
Loss damage waiver (LDW) or collision damage waiver (CDW). This is the big one, and it is not an insurance policy. It is a contractual waiver: the rental company agrees to give up its right to collect from you for damage to, or theft of, its vehicle. Because it isn’t insurance, it isn’t regulated as insurance in most states, and the terms are set entirely by the rental agreement. Waivers commonly void themselves for prohibited use — unauthorized drivers, off-road driving, driving out of the permitted geographic area, and use while impaired are typical.
Supplemental liability insurance (SLI or LIS). This is real liability coverage, sold over the rental company’s underlying limits, protecting you against injury or damage you cause to others.
Personal accident insurance (PAI) and personal effects coverage (PEC). Medical/accidental death coverage for occupants and property coverage for belongings in the car. Both frequently duplicate coverage the renter already carries under health insurance, PIP, or a homeowners or renters policy.
Those are four separate decisions, and declining one does not decline the others.
What a personal auto policy extends to a rental
A standard personal auto policy generally treats a rented private passenger vehicle as a non-owned auto, which means coverage follows the driver into the rental — but with important conditions.
Liability follows. The bodily injury and property damage liability limits on the personal policy generally extend to the rental. That also means the limits carried at home are the limits carried on the trip. A policy at Florida’s minimum $10,000 property damage limit is a $10,000 policy in Denver.
Physical damage follows only if it exists. Comprehensive and collision extend to the rental only if the personal policy carries comprehensive and collision on at least one owned vehicle. Renters carrying liability-only have no physical damage coverage to extend — a common and expensive surprise. Where the coverage does extend, it typically applies on the broadest terms shown on the policy, subject to the applicable deductible.
The deductible applies. Damage to the rental is a first-party claim, paid after the deductible, exactly as it would be on the insured’s own car.
The claim is a claim. A rental damage loss is reported, reserved, and recorded in loss history like any other claim, with the potential rating consequences that carries at renewal.
The four charges people don’t expect
Rental companies bill for more than the sheet metal. These are where the gaps between a rental agreement and a personal auto policy tend to open up.
Loss of use. The rental company’s claim for the revenue the damaged vehicle would have earned while it was out of service. Treatment varies significantly by policy form: some forms address loss of use expenses the insured is legally responsible for, others limit or exclude it. Even where a form responds, the amount a rental company demands and the amount a carrier will pay are frequently not the same number, and the difference lands on the renter.
Diminished value. The claim that the vehicle is worth less after repair than before. Most personal auto policies do not provide first-party diminished value coverage.
Administrative and appraisal fees. Flat charges for processing the damage claim, appearing under various names in the rental agreement.
Towing, storage, and substitute transportation. Charges incidental to the incident that may or may not track what the personal policy pays.
The pattern worth naming: the parts of a rental damage bill that a personal auto policy is least likely to cover are also the parts the renter has the least ability to negotiate.
The Florida wrinkle
Florida addresses primacy by statute. Section 627.7263, Florida Statutes, provides that the liability and personal injury protection insurance covering the lessor of a vehicle for rent or lease is primary — unless the rental or lease agreement states otherwise in at least 10-point type on its face. The statute prescribes the specific language a rental agreement must contain if the renter’s coverage is to be primary instead.
In practice, rental agreements routinely include that opt-out language, which shifts primacy to the renter’s own policy for the statutory minimum limits. The takeaway for a Florida renter is not “the rental company covers it” — it is that the answer is written into the rental agreement, and it is worth reading before signing.
Separately, the federal Graves Amendment (49 U.S.C. § 30106) generally preempts state laws that would hold a rental or leasing company vicariously liable for a renter’s negligence, absent negligence or criminal wrongdoing by the company itself. The practical effect is that an injured third party’s recovery typically runs to the renter and the renter’s coverage.
Credit card coverage: useful, and narrower than assumed
Many cards include rental car damage benefits. The terms matter more than the existence of the benefit.
- Secondary vs. primary. Most cards provide secondary coverage, meaning it applies only after the personal auto policy pays. It can reimburse a deductible; it does not usually replace the claim. A smaller number of cards provide primary benefits.
- Declining the waiver is usually a condition. Buying the LDW typically voids the card benefit.
- It is reimbursement, not payment. The cardholder generally settles with the rental company first and submits documentation afterward.
- Exclusions are common. Excluded vehicle classes (trucks, exotics, large vans, some SUVs), excluded countries, and rental periods beyond a stated number of consecutive days are all typical.
- It is not liability coverage. Card benefits address damage to the rental vehicle, not injury or damage the renter causes to others.
Anyone planning to rely on a card benefit should request the card’s current benefit guide and read the exclusions before the trip, not at the counter.
Negotiated rate programs
Some insurers, employers, and associations maintain negotiated rate agreements with rental companies, accessed through a discount or corporate code at booking. Depending on the specific agreement, these programs may include some combination of a discounted rate, waived additional-driver fees, waived or capped loss of use charges, expanded permitted-driver definitions, and a damage waiver built into the rate.
Terms differ by program and change over time, so the only reliable move is to confirm what a specific code includes — in writing — before relying on it.
Business and employee rentals
When the rental is for business, the analysis moves to the commercial side. A business auto policy can be endorsed for hired auto liability and hired auto physical damage, and the presence or absence of hired physical damage is the single most common gap found when an employee damages a rental on company time. Employees renting in their own name, personal policies with business-use exclusions, and rentals of trucks or vans outside the private passenger definition all warrant a coverage review before the reservation, not after the accident.
Why the odds are different in a rental
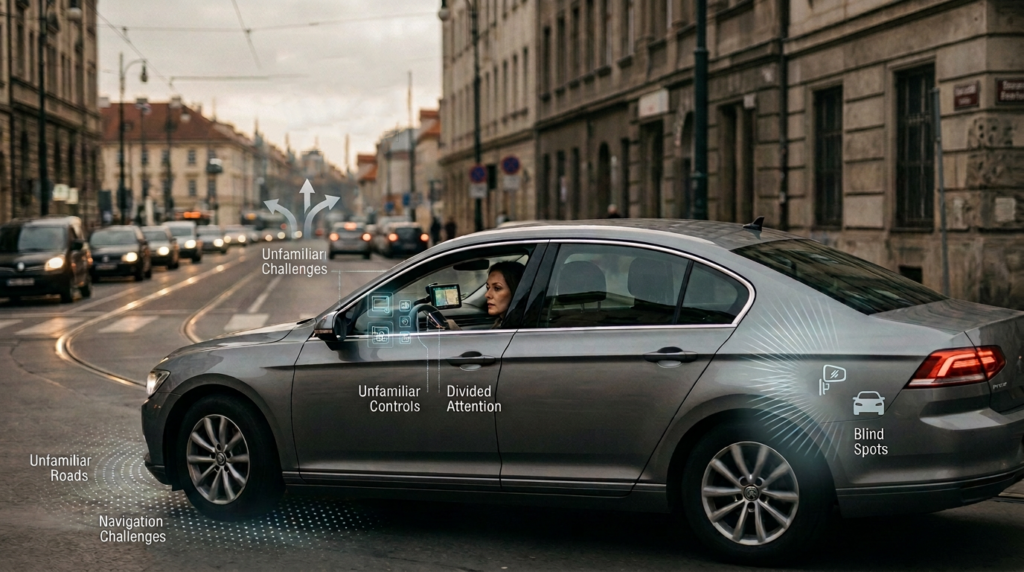
Underwriting prices probability of loss. Several things about renting raise it, all at once:
- The vehicle is unfamiliar — different size, weight, braking, acceleration, and turning radius than the driver’s own car
- Sightlines and blind spots are different, and any aftermarket aids the driver relies on at home (spot mirrors, in particular) are not there
- Camera and sensor behavior differs, or the features are absent
- The roads are unfamiliar
- Attention is split between navigation prompts, street signs, and traffic instead of being on traffic alone
- The driver is often tired, on a schedule, and driving straight out of an airport
None of these are dramatic on their own. Together, they describe a driver operating at a meaningfully higher probability of loss than on any ordinary day at home.
The arithmetic
The waiver is priced per day, and at the counter it is compared against the daily rate — which is exactly the comparison that makes it feel expensive.
The more useful comparison is against the exposure: the deductible, plus loss of use, plus diminished value, plus administrative charges, plus the time spent managing a claim, plus the effect of a chargeable loss at renewal. Set against the total cost of the trip it protects, a waiver is usually a small line item. Set against the daily rate, it never looks like one.
Before declining the waiver, confirm five things
- Does the personal auto policy carry comprehensive and collision? If not, there is no physical damage coverage to extend.
- What is the deductible, and is that amount available on short notice?
- What does the policy form say about loss of use, and what is the limit?
- If a credit card benefit is part of the plan — is it primary or secondary, and does this vehicle class and rental length qualify?
- Is the vehicle a private passenger auto, or a truck, van, or specialty vehicle that falls outside the policy’s non-owned auto definition?
Anyone who can’t answer all five before reaching the counter should treat that as the answer.
The takeaway
- A personal auto policy follows the driver into a rental, but it does not follow the rental agreement. The charges that aren’t damage — loss of use, diminished value, administrative fees — are where the gaps live.
- Credit card benefits are usually secondary, usually conditional on declining the waiver, and always narrower than the marketing suggests.
- In Florida, whether the renter’s coverage or the rental company’s is primary is determined by language in the rental agreement, under Fla. Stat. § 627.7263.
- Driving an unfamiliar vehicle on unfamiliar roads is a higher-probability situation than an ordinary day of driving, and the waiver is priced against a comparison that makes it look worse than it is.
This article is general information about how coverage typically works and is not a statement of coverage, legal advice, or a recommendation regarding any particular policy or product. Coverage is determined solely by the terms, conditions, limits, and exclusions of the policy actually issued, by the terms of the rental agreement, and by the facts of a given claim. Policy forms, credit card benefits, and rental company programs vary and change. Review your own policy and rental agreement, or contact a licensed agent, before relying on anything here.
Cronin Insurance Agency · Boca Raton, FL · Serving Palm Beach, Broward, and Miami-Dade Counties