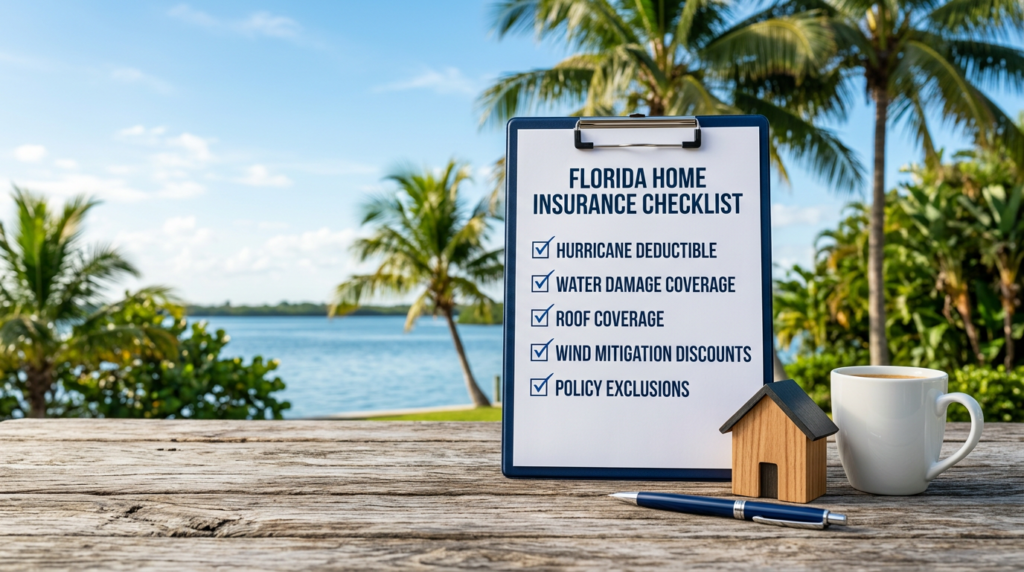
Shopping for home insurance in Florida is not just about finding the lowest price. The right policy comes down to five questions most homeowners never think to ask: What is your hurricane deductible? What water damage is actually covered? How does your insurer handle your roof? Are your wind mitigation credits being applied? And what exclusions are different between policies? Get the answers right, and you get the right coverage. Skip them, and you could be seriously underinsured when a storm hits.
Why Shopping for Home Insurance in Florida Is Different
Florida homeowners face risks that simply don’t exist most other states. According to the Florida Office of Insurance Regulation, Florida accounts for a disproportionate share of U.S. property insurance claims — driven by hurricane exposure, heavy rainfall, high rebuild costs, and a volatile market where multiple carriers have left the state in recent years.
That means policies here have more conditions, carve-outs, and Florida-specific rules than policies almost anywhere else. Price alone doesn’t tell you what you’re getting. You have to look at what each policy actually covers — and what it doesn’t.
In Palm Beach County and Boca Raton, an independent agent can compare options across multiple carriers on your behalf. Visit our home insurance page to get started.
What Is My Hurricane Deductible — and How Much Could I Owe?
Your hurricane deductible is separate from your regular deductible — and it works differently. Instead of a flat dollar amount, it’s usually a percentage of your home’s insured value. That percentage is typically 2–5%.
Here’s what that means in practice: on a home insured for $400,000, a 2% hurricane deductible means you pay $8,000 out of pocket before your policy covers anything. A 5% deductible means $20,000. That’s a big difference — and it’s one of the most important things to compare when you’re shopping.
Always ask: What is the hurricane deductible percentage, not just whether there is one. Also ask whether the deductible applies per storm or per season.
What Type and Amount of Water Coverage Do I Have?
Not all water damage is treated the same way in a home insurance policy. Most policies cover sudden and accidental water damage — like a pipe that bursts inside your home. But many exclude slow leaks, seepage, mold, or damage that built up gradually over time.
Flooding from outside your home is never covered by a standard policy. That includes storm surge, rising water from a hurricane, and heavy rain runoff. For that, you need separate flood insurance.
When comparing policies, ask these specific questions:
- What types of water damage are covered?
- Is there a sublimit on water damage claims?
- Is mold remediation included, and up to what amount?
- Does the policy cover backup from a drain or sewer?
How Is My Roof Covered?
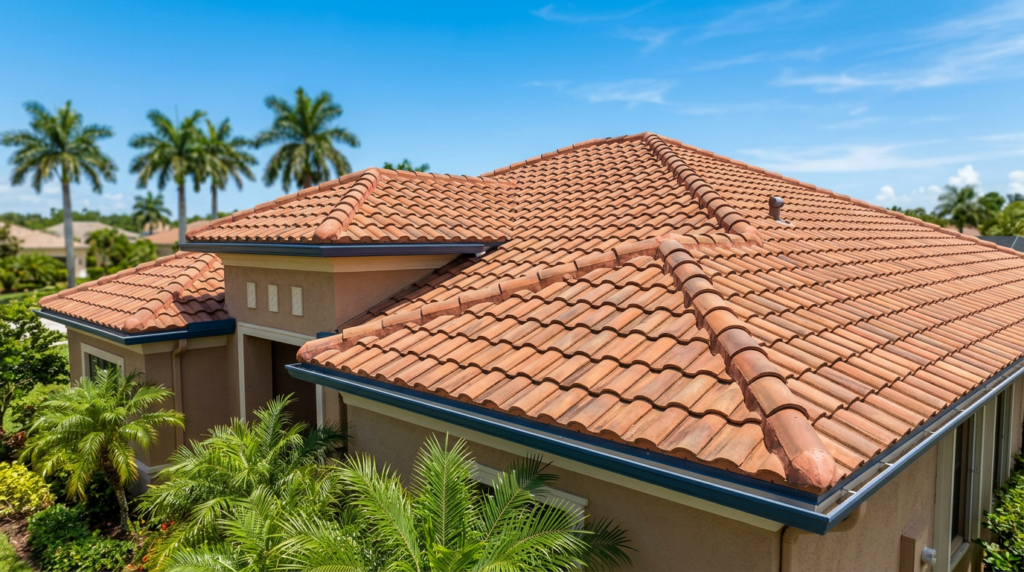
In South Florida, your roof is one of the most valuable parts of your home — and one of the most important things to compare between policies. There are two main ways insurers cover roofs, and the difference can cost you tens of thousands of dollars.
Replacement cost value (RCV): The insurer pays to replace your roof at today’s prices, regardless of its age.
Actual cash value (ACV): The insurer factors in depreciation. On a 15-year-old roof, ACV coverage might pay only 30–40% of what a new roof actually costs — leaving you to cover the rest.
Ask each insurer: Does my policy cover roof replacement at full replacement cost or actual cash value? Is there a separate roof deductible? Does my roof’s age affect my coverage or my eligibility?
Are All My Wind Mitigation Credits Being Applied?
Wind mitigation credits can significantly lower your home insurance premium in South Florida — sometimes by 20–40%. If your home has hurricane shutters, impact-resistant windows, a hip roof, or reinforced garage doors, you may qualify for these discounts.
But here’s the catch: you have to get a wind mitigation inspection done by a licensed inspector and submit the report to your insurer. Many homeowners have qualifying features and don’t know it — or had an inspection done years ago and never submitted it.
When shopping for a new policy, ask each insurer:
- Do you accept my current wind mitigation inspection report?
- What features qualify for discounts under your policy?
- How much could my premium be reduced with a current inspection?
What Exclusions or Limitations Are Different Between Policies?
Every home insurance policy has exclusions. The real question when shopping is: which exclusions are different from one policy to the next? Those differences tell you which policy is actually better for your specific home and situation.
Common exclusions and limitations to compare in Florida:
- Sinkhole coverage: Required by Florida law, but handled differently by each insurer. Ask how claims are processed and what’s covered.
- Screen enclosures and pool cages: Often subject to sublimits or excluded entirely. Important in South Florida where these are common.
- Detached structures: Fences, sheds, and detached garages may have separate limits. Know what yours are.
- Ordinance or law coverage: If your home is damaged and needs to be rebuilt to current building codes, this coverage pays the difference. It is often undervalued — and the difference in cost between policies can be significant.
Ask each insurer to explain what’s different in their policy compared to a standard policy. A good agent will walk you through this — not just hand you a price.
Frequently Asked Questions
What questions should I ask when shopping for home insurance in Florida?
Ask about your hurricane deductible percentage, what water damage is covered, whether your roof is covered at replacement cost or actual cash value, whether your wind mitigation credits are being applied, and what exclusions are different from a standard policy. These five areas have the biggest impact on how well your policy protects you.
What is a hurricane deductible and how does it work in Florida?
A hurricane deductible is a separate deductible that applies specifically to damage caused by a named hurricane. In Florida, it’s usually 2–5% of your home’s insured value — not a flat dollar amount. On a $400,000 home, a 2% hurricane deductible means you pay $8,000 before your insurer covers the rest.
Does homeowner’s insurance in South Florida cover all water damage?
No. Standard policies cover sudden and accidental water damage inside your home — like a burst pipe. They do not cover flooding from outside, slow leaks, or most mold damage. For flood damage from storms or rising water, you need a separate flood insurance policy.
How do wind mitigation credits lower my home insurance premium in Boca Raton?
Wind mitigation credits reward homeowners who have features that reduce hurricane damage — like impact windows, hurricane shutters, or a hip roof. A licensed inspector documents these features and submits a report to your insurer. Credits can reduce your premium by 20–40%. Many homeowners in Boca Raton qualify but have never had the inspection done.
What is ordinance or law coverage and do I need it in Florida?
Ordinance or law coverage pays the additional cost of rebuilding your home to current building codes after a covered loss. In Florida, where building codes have changed significantly after major storms, this can make a substantial difference in a claim. Most standard policies include some, but the limits vary — ask specifically what your policy covers.
Can Cronin Insurance help me compare policies and find the right coverage?
Yes. Cronin Insurance is an independent agency that works with 10+ home insurance carriers in Florida. We compare policies side by side — not just on price, but on what they actually cover. Visit our home insurance page or call us to get started.
Ready to Shop Smarter for Home Insurance?
An independent agent compares policies across multiple carriers and explains the real differences — not just the price. Cronin Insurance has served South Florida homeowners for over 30 years.
📞 Call: (561) 479-1898 | 💬 Text: (561) 475-5606 | 🌐 cronininsurance.com/home-insurance
Low rates, choice of companies, and personal advice from local agents. When it comes to shopping for home insurance in South Florida, Cronin Insurance is the Wise Choice.